English
 Français


In a market where capacity is abundant, the search for new growth drivers is prompting insurers and reinsurers to develop solutions tailored to emerging risks.
The protection gap, therefore, represents a new opportunity for growth. Cyber insurance, coverage for data centers dedicated to artificial intelligence (AI), AI-related liability, and insurance for renewable energy infrastructure are among the lines of business with high growth potential.
Cyber insurance
The cyber insurance market continues to exhibit strong growth potential. In this sector, global premiums are projected to reach 16.4 billion USD by 2026, even as coverage remains limited. Only 5 to 10% of microenterprises and 10 to 20% of small and medium-sized enterprises (SMEs) are insured against this type of risk.
Insurance plans for AI-dedicated data centers
The growth of data centers dedicated to artificial intelligence (AI) is creating increasing insurance needs.
According to Swiss Re (1), major technology companies are expected to invest nearly 750 billion USD in AI-related infrastructure starting in 2026. These facilities, which are costly and often geographically concentrated, are exposed to extreme weather events, power outages, cooling system failures, and supply chain disruptions. All these incidents are likely to cause significant property damage, business interruptions, and substantial operating losses.
Global insurance premiums pertaining to data centers currently amount to 10.6 billion USD and are poised to reach 24.2 billion USD by 2030.
Over the 2026–2030 period, these premiums are set to amount to nearly 91 billion USD, a real new growth opportunity for insurers and reinsurers, though it requires rigorous management of accumulation risks.
(1) Sigma insights 07/2026, Insuring AI: data centre value accumulation risks
AI-related liability
Liability related to artificial intelligence poses another emerging risk to the insurance market. Algorithmic errors, erroneous decisions, or AI-generated content can be prejudicial to users and third parties.
These risks include:
- AI errors and malfunctions: a system provides incorrect information, makes a wrong decision, or generates inaccurate results.
- Prejudice caused to third parties: discrimination, damage to reputation, copyright infringement, or disclosure of confidential data.
- Operational failure: a system executes an incorrect instruction and causes financial losses or property damage.
These situations are driving the development of specific insurance coverage, creating new growth opportunities for insurers and reinsurers.
Renewable energy infrastructure
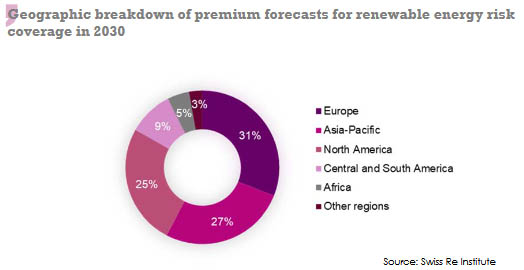
The energy transition represents another growth driver for the market. According to some sources, investments in renewable energy infrastructure is poised to generate 111 billion USD in cumulative premiums between 2026 and 2030.
The development of these facilities increases the need for coverage related to construction, property damage, and business interruption, particularly in the face of climate-related risks and technical failures.
Business interruption
Business interruption represents a growing challenge for the insurance market. A power outage, technical failure, or supply disruption can significantly prolong production downtime, resulting in substantial operating losses, sometimes far exceeding direct property damage.
Ageing population and long-term care insurance
Coverage for the “loss of autonomy” risk represents a market with strong potential. The ageing of the global population is driving demand for long-term care insurance.
According to the World Health Organization (WHO), the number of people aged 60 and older is projected to rise from 1.4 billion in 2030 to 2.1 billion in 2050, while the number of people over 80 is expected to reach 426 million.
Increased life expectancy is, therefore, coupled with growing needs for care related to the loss of autonomy. In the insurance sector, this market remains underdeveloped in many countries. Its growth will depend on the industry’s ability to offer affordable coverage, pool risks, and manage liabilities that may span several decades.